Inovance Q3 2026 Earnings
The other pillar of Chinese automation reported the same week.
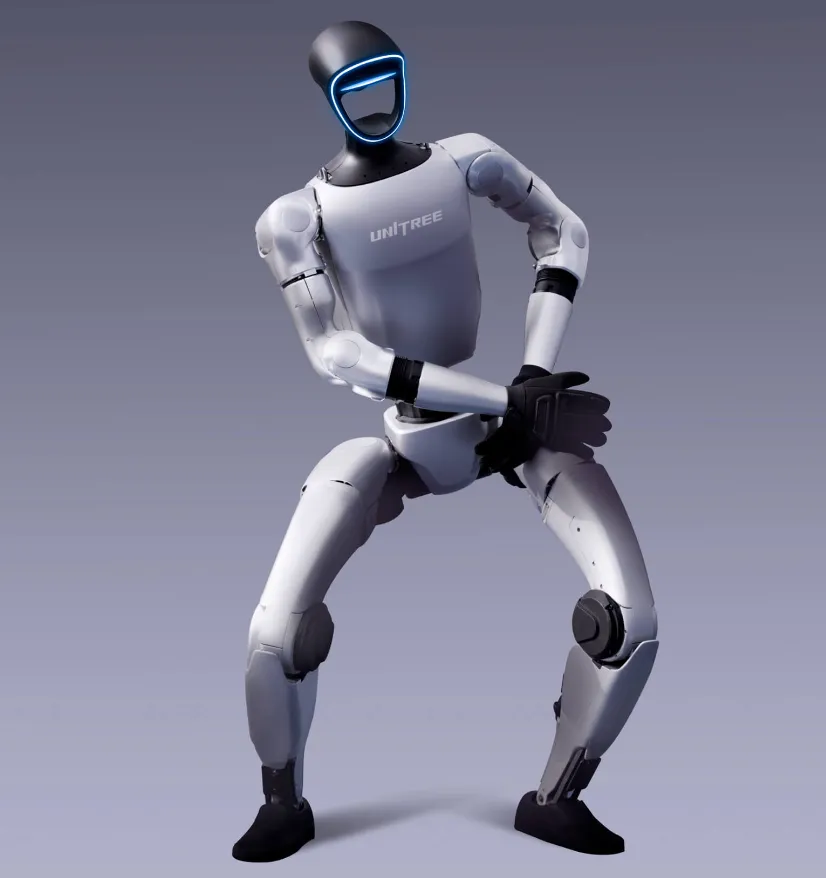
On the evening of October 28, Unitree Robotics (688836.SH) filed its third-quarter report — its first earnings since the August 19 STAR Market IPO. The headline numbers look split: revenue growth actually accelerated, but net profit fell. The cause is neither weakness nor a problem, exactly — it is a deliberate, very large bet on embodied-AI foundation models. Here is the full read, built only on the official filing and verified broker reporting.
| Metric | Q3 standalone | YoY | 9M cumulative | YoY |
|---|---|---|---|---|
| Revenue | ¥665M | +69.93% | ¥1.817B | +55.71% |
| Net profit (attributable) | ¥113M | −17.37% | ¥387M | +270.54% |
| Recurring net profit (扣非) | ¥105M | −17.42% | ¥349M | −18.78% |
| Gross margin | 50.58% | — | 54.02% | −5.73 pct |
| R&D expense | ¥127M | +249.58% | ¥263M | +191.48% |
| R&D as % of revenue | 19.10% | +9.82 pct | 14.47% | +6.74 pct |
| Operating cash flow | — | — | ¥194M | −54.69% |
Source: Unitree 2026 Q3 report (cninfo/SSE, Oct 28); Dongwu Securities note dated Oct 29. The 9M net profit growth of +270% is against a prior period depressed by a large one-off share-based compensation charge; the recurring (扣非) line is the cleaner read.
Two things happened at once. Revenue accelerated from +48.5% in H1 to +69.9% in Q3 — the G1 humanoid line and quadruped shipments are still scaling, and the product mix (humanoids were 51.8% of 2025 revenue, quadrupeds 41.6%) is broadening. But R&D nearly tripled to ¥127M in the quarter, adding about ¥91M of expense year-on-year, which is almost exactly the swing that turned a revenue beat into a profit miss.
The company's own explanation is explicit: spending went to "embodied-AI large-model R&D and compute, plus expanding the engineering team." This is not a one-off cost — it is a strategic pivot. At the October 22 World Physical AI Conference in Hangzhou, Wang Xingxing named three priorities: (1) scale production, (2) build physical-AI small models tailored to Unitree hardware, and (3) stand up an ultra-large compute cluster. The company is pre-researching what it calls a "self-evolving V1.0" physical-AI foundation model, and showed off the Dex5-S five-finger dexterous hand alongside industrial, commercial and education reference setups.
Gross margin also compressed: 54.02% for the nine months vs 60.44% in FY2025, and just 50.58% in Q3. That is consistent with earlier evidence that humanoid margins have slid from 87.7% (2023) to ~63% (2025) as G1+ pricing, components and scaling costs weigh.
Investors worried about a demand slowdown should look at two working-capital lines instead of the P&L:
The offset: operating cash flow fell 54.7% to ¥194M as procurement, payroll and R&D cash outflows grew with revenue. That is normal for a company ramping working capital ahead of delivery, but Q4 collections are the proof point.
| View (post-report) | Detail |
|---|---|
| Stock / market cap | ¥695.9 close; ~¥281.5B (~$39B); 52-week range ¥404 – ¥1,100 |
| Dongwu Securities (Oct 29) | Buy, first coverage; 2026E net ¥552M, 2027E ¥916M, 2028E ¥1.508B |
| Implied P/E | ~510x (2026E) / 307x (2027E) / 187x (2028E) |
| Revenue forecasts (Dongwu) | ¥2.627B (2026E) / ¥4.313B (2027E) / ¥5.953B (2028E) |
Source: Dongwu Securities note, Oct 29, 2026; closing price ¥695.90. Earlier sell-side views were split (JPMorgan Underweight at ¥300 target; Nomura ¥370); Dongwu is the first post-IPO note to underwrite the model-and-compute pivot explicitly.
At ~510x forward earnings, the stock is not pricing in the current P&L — it is pricing in the chance that Unitree becomes not just the world's humanoid hardware leader (5,511 units shipped in 2025, ~32% global share) but also a physical-AI software platform. The Q3 R&D surge is the down payment on that bet. Whether the "self-evolving V1.0" model actually lands, and whether it widens Unitree's hardware moat, is what 2027–2028 earnings multiples depend on.
The same evening as the report, Unitree announced a ¥20M capital increase into the Hangzhou Embodied AI Application Pilot Base (a JV controlled by Hangzhou state capital), keeping its 10% stake. The pilot base is still investment-stage (9M revenue ¥0.45M, net loss ¥15.2M), so this is an ecosystem/policy play rather than a revenue line.
Q3 revenue was 665 million yuan (+69.93% YoY), net profit attributable to shareholders was 113 million yuan (−17.37%), and recurring net profit was 105 million yuan (−17.42%). For the nine months, revenue reached 1.817 billion yuan (+55.71%) and net profit was 387 million yuan, though recurring profit fell 18.78%.
Q3 R&D spending tripled to 127 million yuan (+249.58%), 19.1% of quarterly revenue, as Unitree invested in embodied-AI foundation models, compute clusters and headcount. Gross margin also compressed to 50.58% in Q3 from roughly 60% a year earlier.
Yes on the balance sheet: contract liabilities (customer prepayments) rose 70.2% to 233 million yuan, and inventory more than doubled to 1.019 billion yuan (+177%), which management frames as stockpiling to support Q4 and 2026 deliveries.
Founder Wang Xingxing says the priorities are scaling production, building physical-AI small models tuned to Unitree's own robots, and standing up an ultra-large compute cluster. The company is pre-researching a "self-evolving V1.0" physical-AI foundation model and showed the Dex5-S five-finger dexterous hand.
Unitree closed at 695.9 yuan after the report, market cap about 281.5 billion yuan. Dongwu Securities initiated coverage on October 29 with a Buy rating and 2026–2028 net profit forecasts of 552M / 916M / 1.508B yuan, implying P/E of roughly 510x / 307x / 187x.
Disclaimer: China Robotics Insider is an independent editorial site. Nothing on this page is investment advice; every figure should be verified against the official SSE/cninfo filing before any decision.
The other pillar of Chinese automation reported the same week.
The October 21 product launch behind Q4 shipments.
The component supply chain Unitree buys from.
How public-market investors are trading the sector.
We are interpreting every major China robotics earnings release as it lands.