China AMR & AGV Suppliers vs Locus, MiR, GreyOrange
Geek+, Quicktron, Seer Robotics and VisionNav vs Western AMR leaders - specs, price, navigation and where Chinese vendors already win.
2026-09-23Beyond the names and numbers — analysis of the forces driving the world's fastest-moving robotics ecosystem. New articles added as the industry moves.
Geek+, Quicktron, Seer Robotics and VisionNav vs Western AMR leaders - specs, price, navigation and where Chinese vendors already win.
2026-09-23
Top Chinese suppliers (Leaderdrive, Laifual, Hans), price ranges, MOQ, lead times and red flags — sourcing harmonic reducers 40-70% cheaper than Japanese HD.
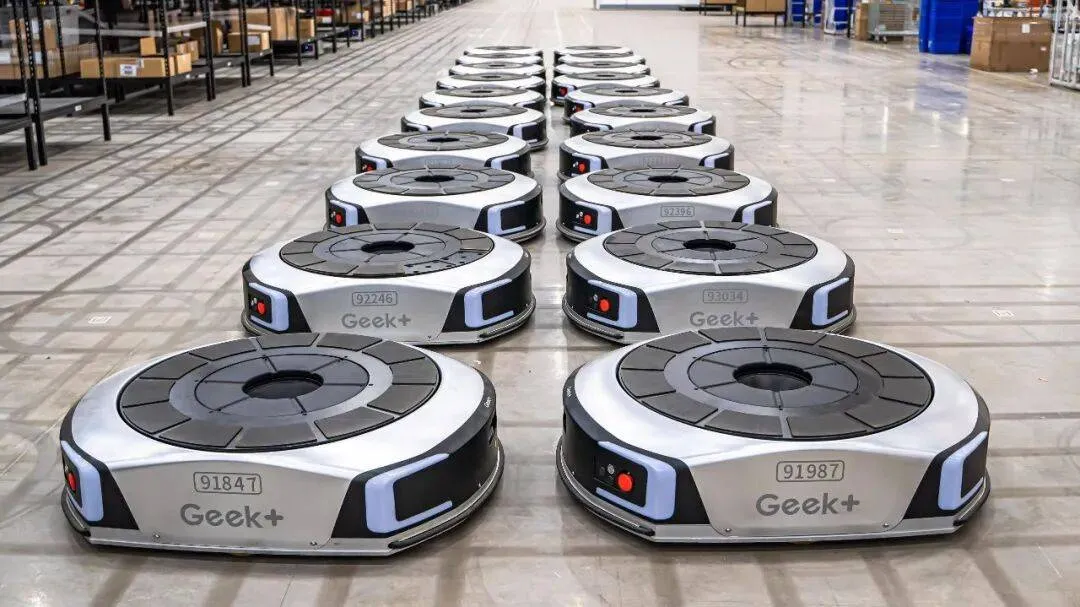
Geek+ (极智嘉) has shipped 20,000+ AMRs to Decathlon, Walmart, DHL. Product line, specs and how it compares to Amazon Kiva and Hai Robotics.
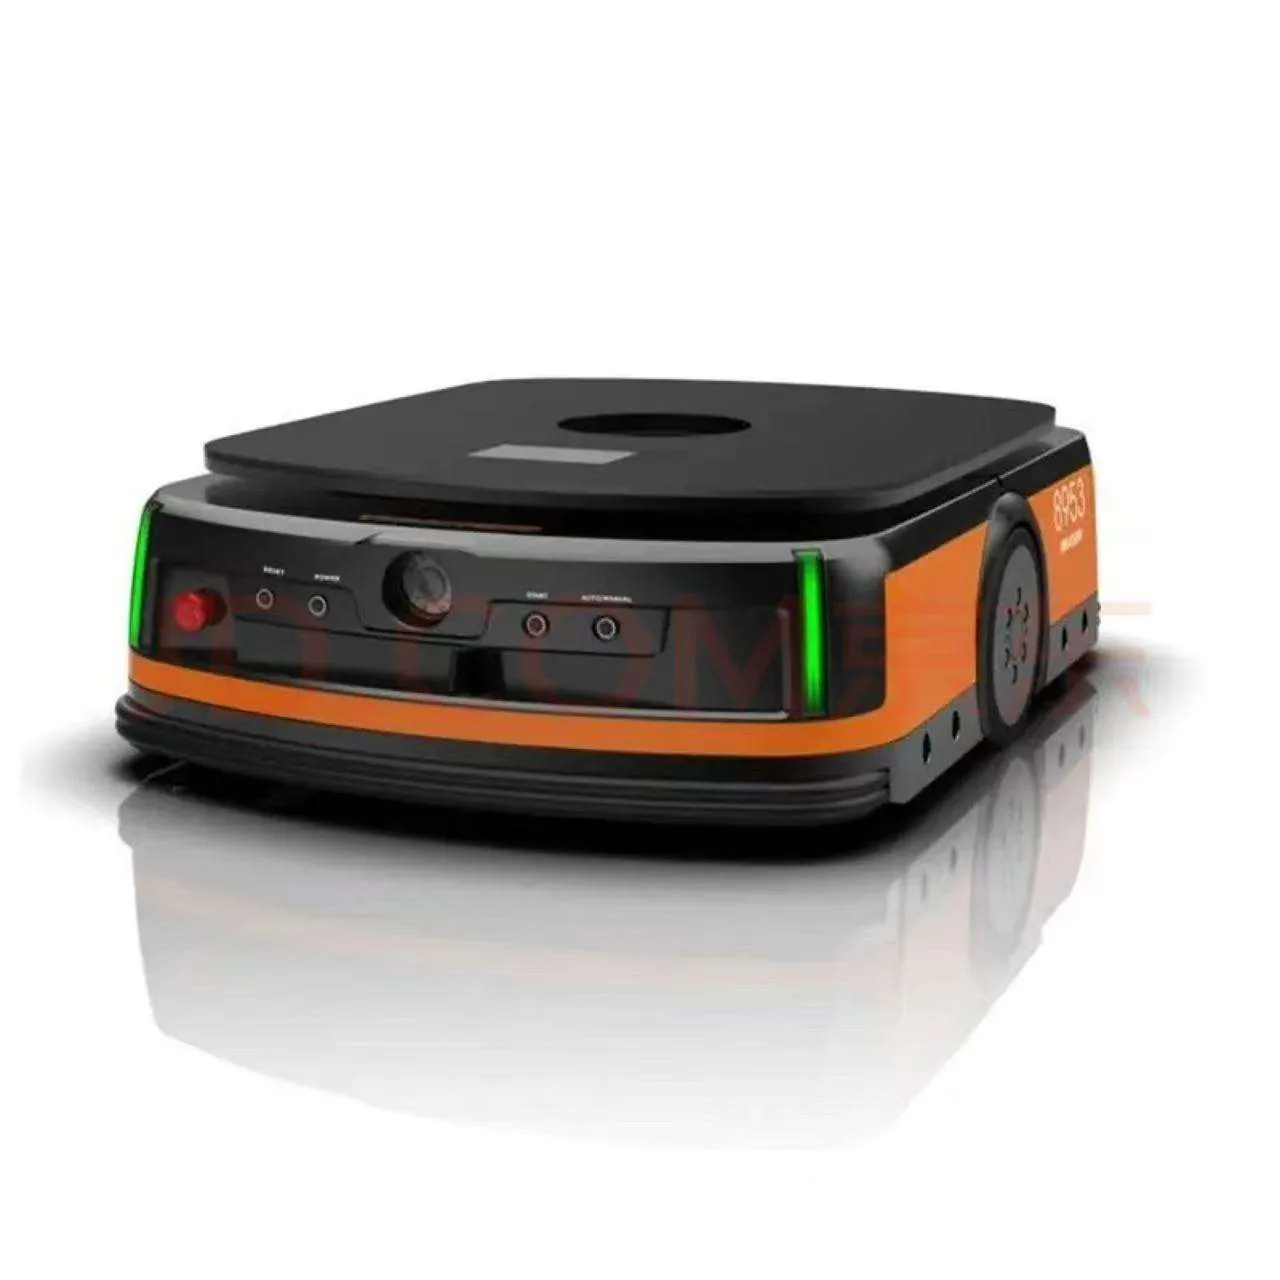
An ACR rides on top of racking and picks individual totes — a category invented by Shenzhen's Hai Robotics. Compare ACR vs AGV/AMR and the top Chinese vendors in 2026.
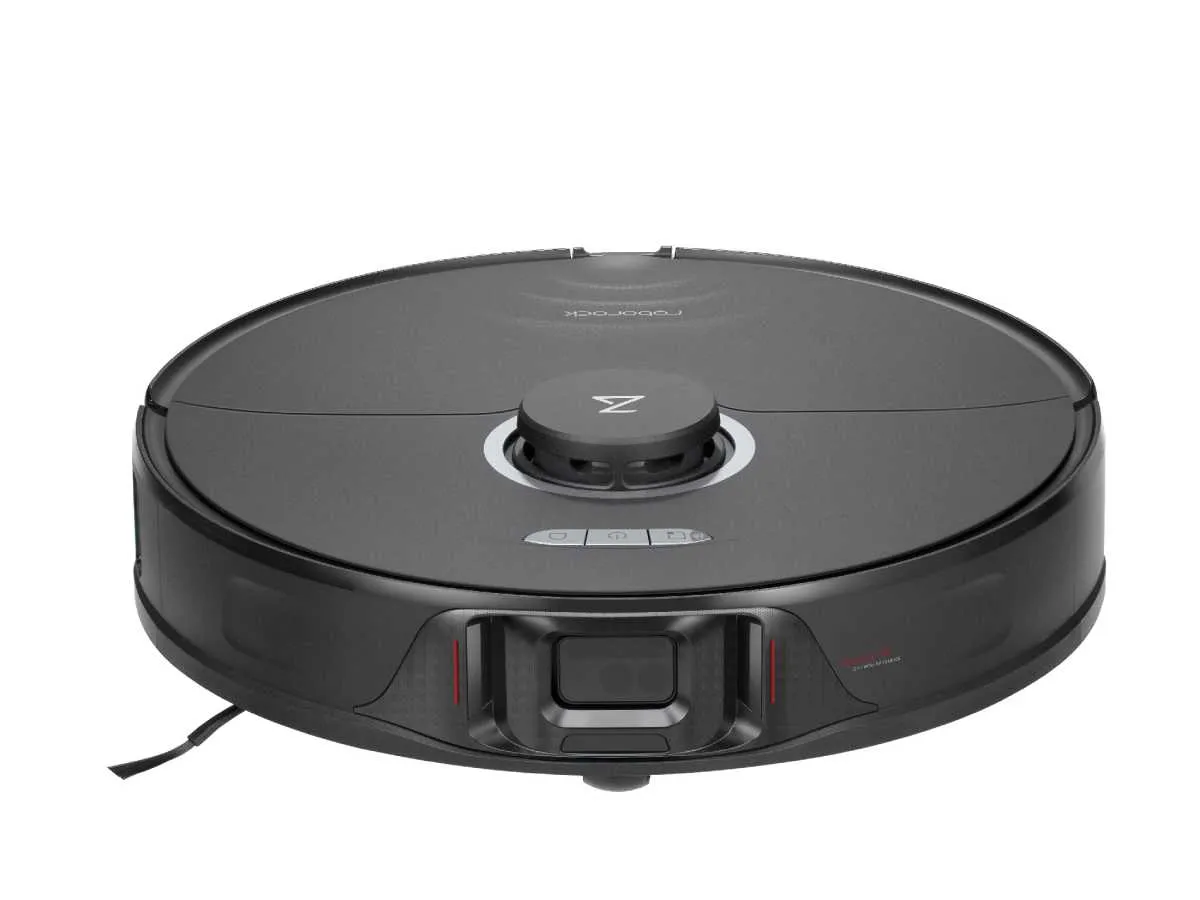
Roborock is Beijing-based Roborock Technology (石头科技, 688169.SH). It grew out of Xiaomi ecosystem but is independently listed — here is the full ownership breakdown vs Ecovacs and Dreame.
Swiss GSA & Rollvis hold >50% of the world's roller screws — the $1,350-2,700 actuators inside every humanoid leg. China still imports 80-85%, but prices collapsed from ¥10,000 to ¥2,000 and Shuanglin is building a 100,000-unit line.
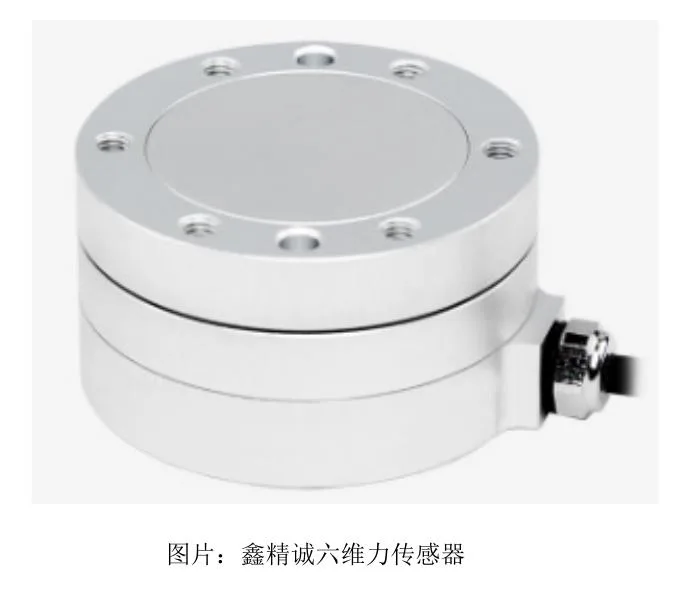
ATI owned the robot industry's sense of touch for 30 years. In 2025 Chinese suppliers took 92.8% of China's humanoid F/T sensor market — Bluetech at 80.3% — at a third of ATI's price.
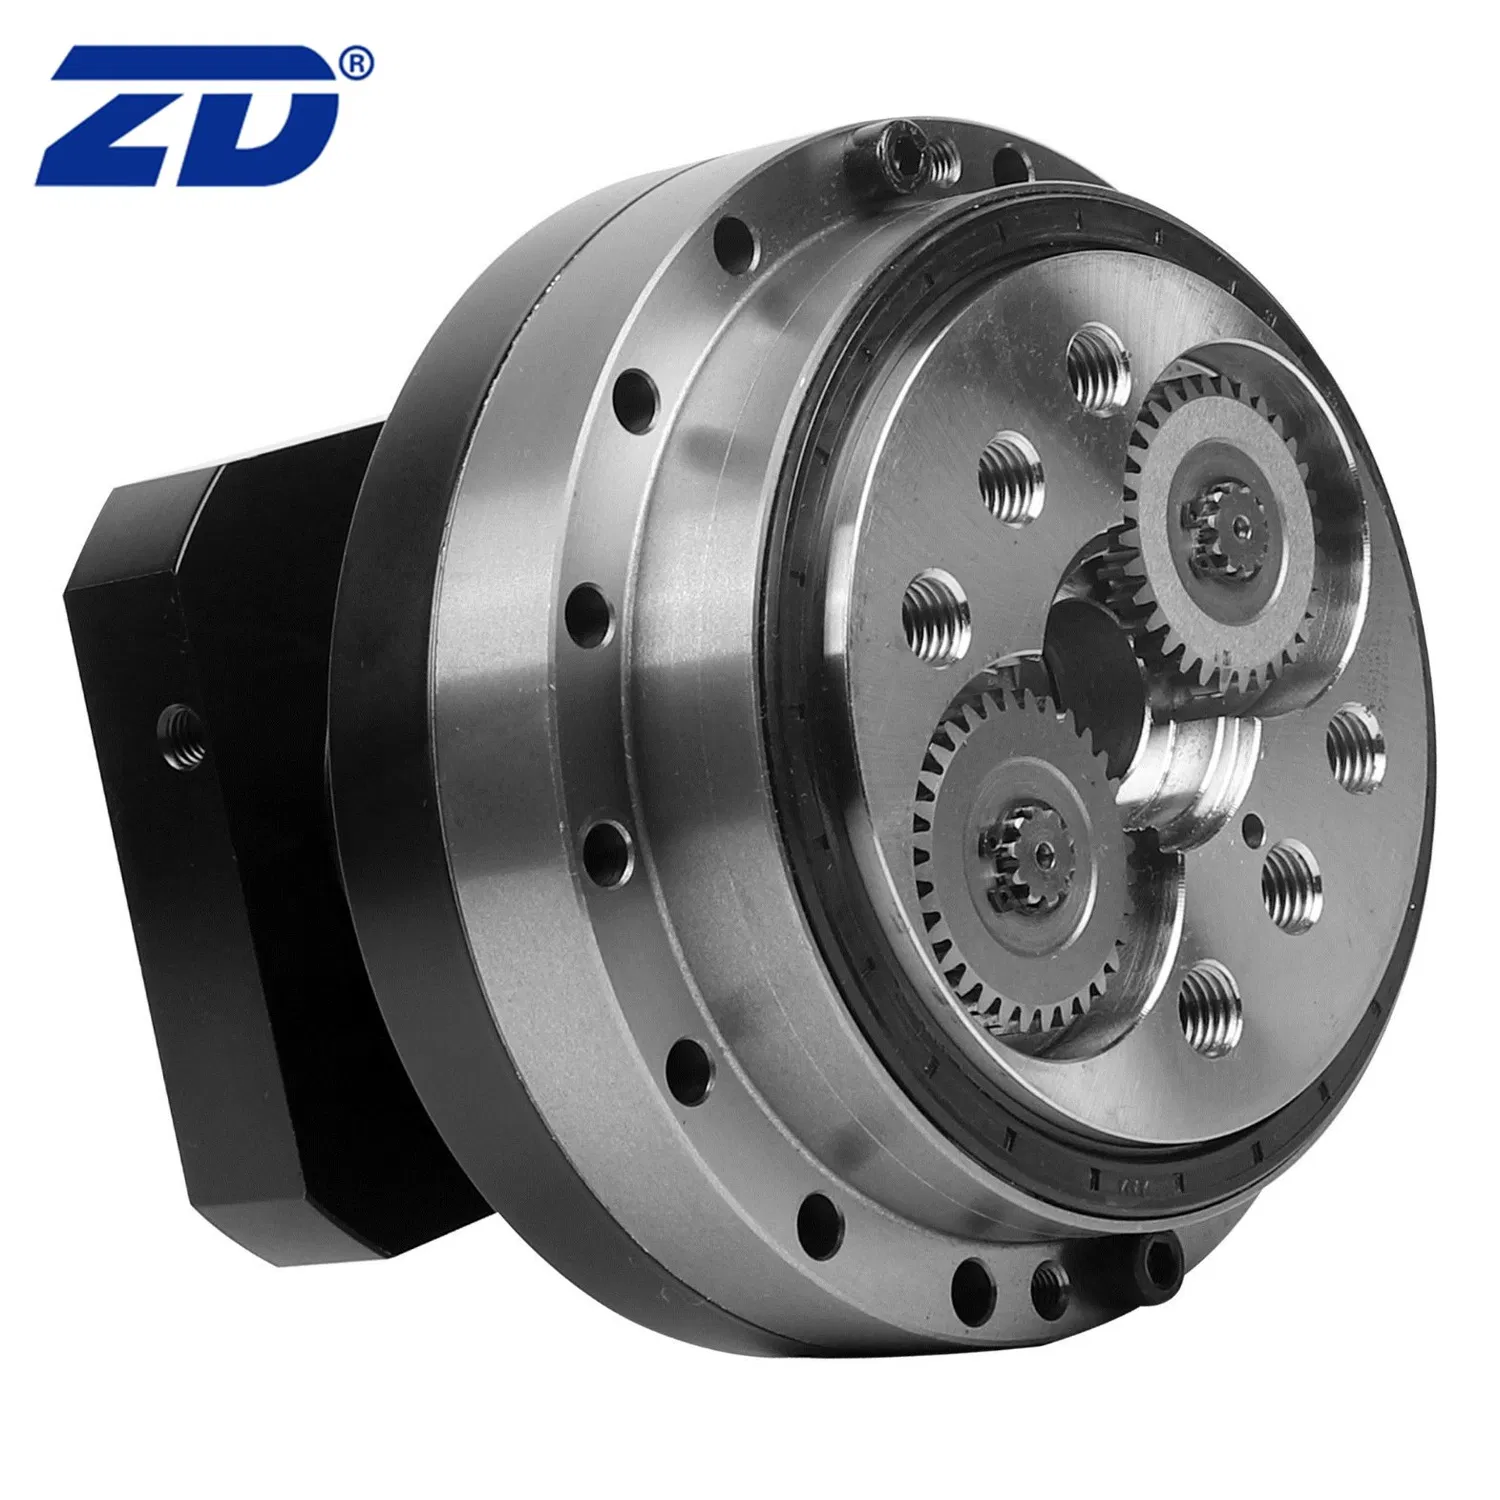
One Japanese company still owns ~60% of the world's RV reducers. Shuanghuan reached 24.98% domestic share, ships into Tesla Optimus' waist, and cut the average price to ¥2,950.
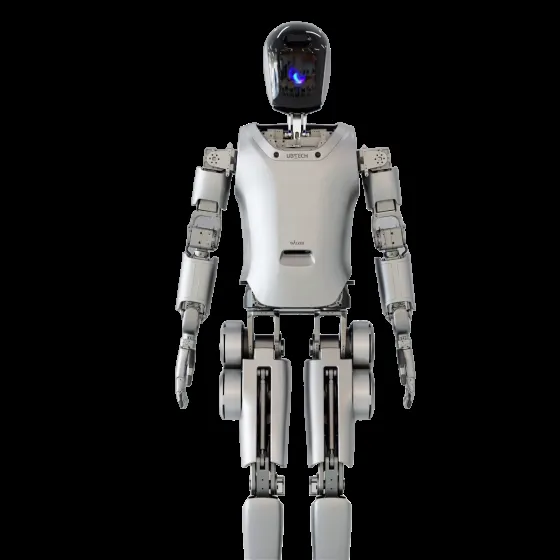
The first mass-market companion humanoid ships Sep 16: 88 DoF, RMB 119,800-990,000, 13,361 pre-orders. How it stacks up against Tesla Optimus — and the delivery test ahead.
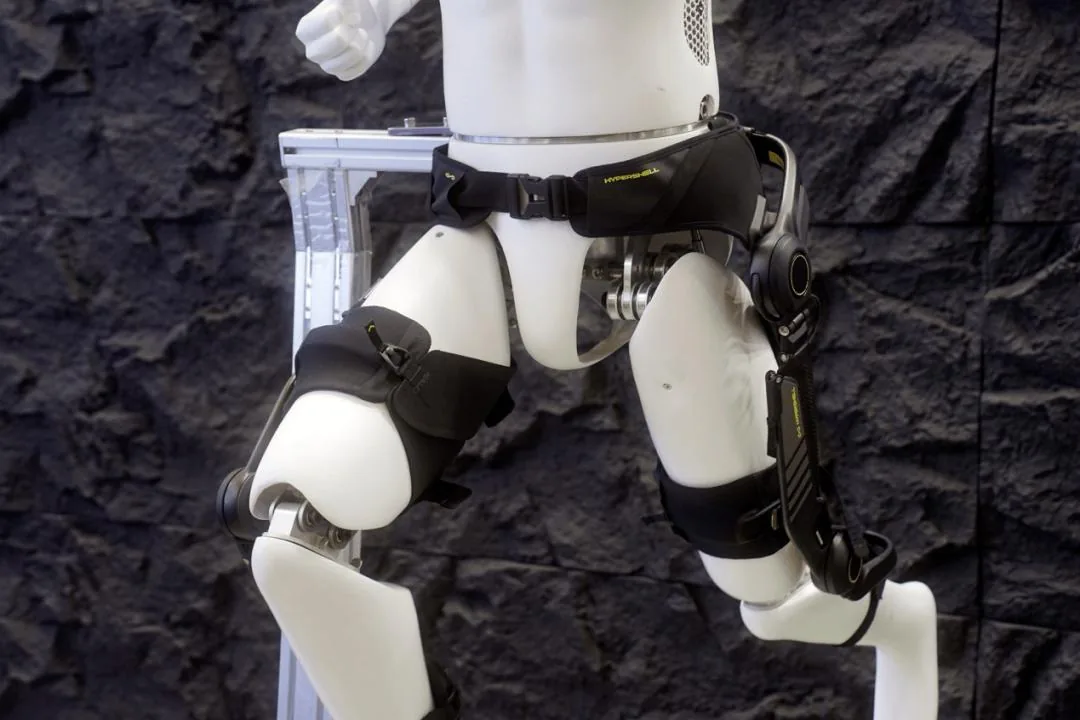
IDC's first China report \u2014 \u00a51.6B market, medical vs consumer split, Hypershell Halo, and the insurance trigger about to open a ten-billion-yuan market.
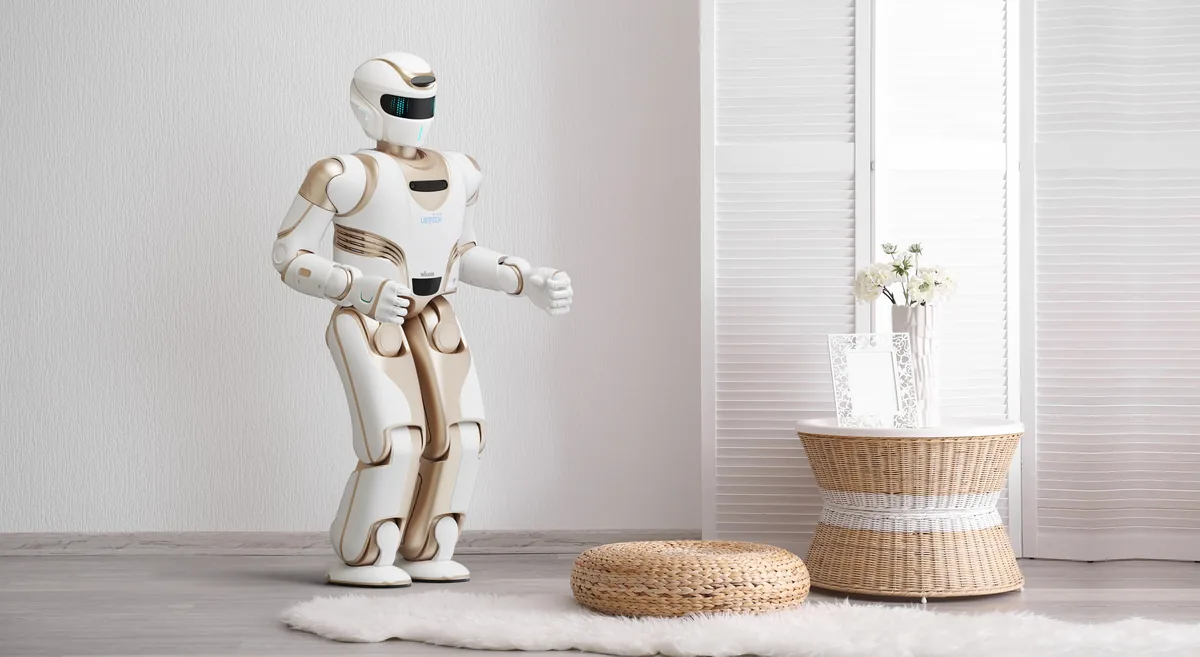
UBTECH's Walker X in 237 nursing chains, Fourier's GR-3 Care-bot, Leju's Kuafu \u2014 the race to serve 320 million seniors.
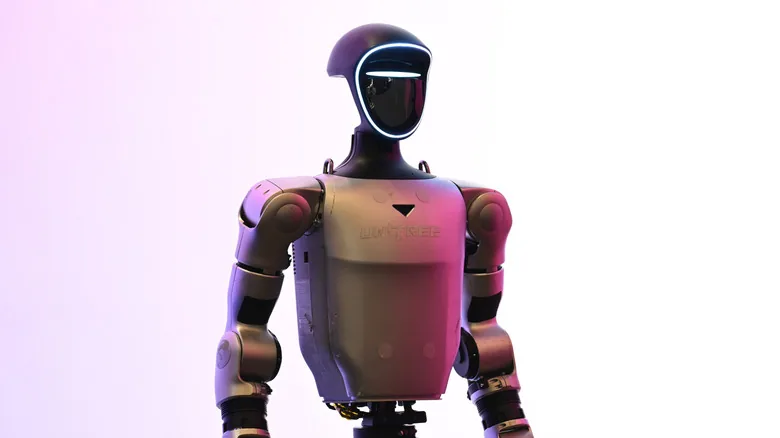
AgiBot 44%, Unitree 31% of global shipments \u2014 and robot exports are up 210% YoY. Who sells abroad, where the robots go, and the three-stage playbook.
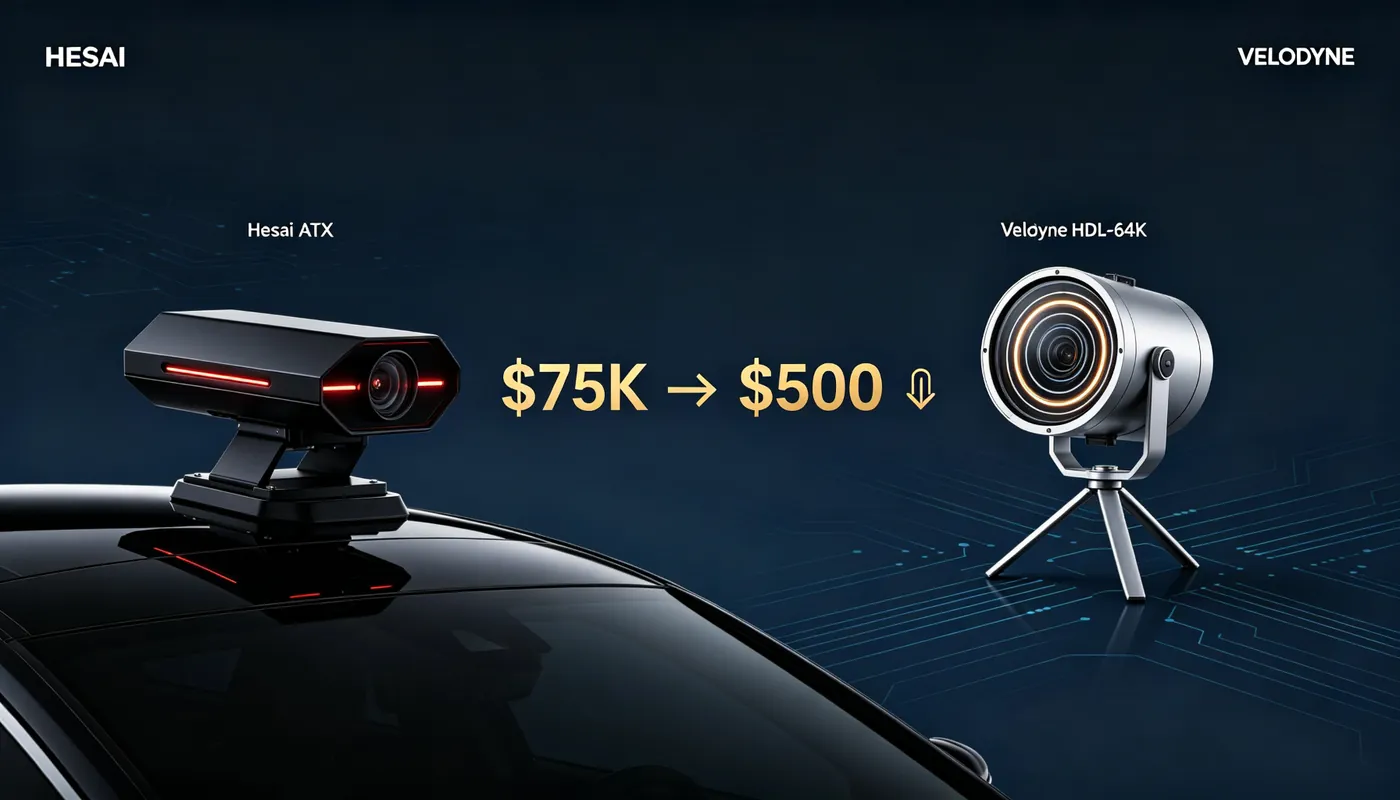
Velodyne's HDL-64E cost $75,000 in 2017. Hesai ships automotive long-range lidar for under $500 and owns 43% of the market. The 99.5% cost collapse that ended the American pioneer.
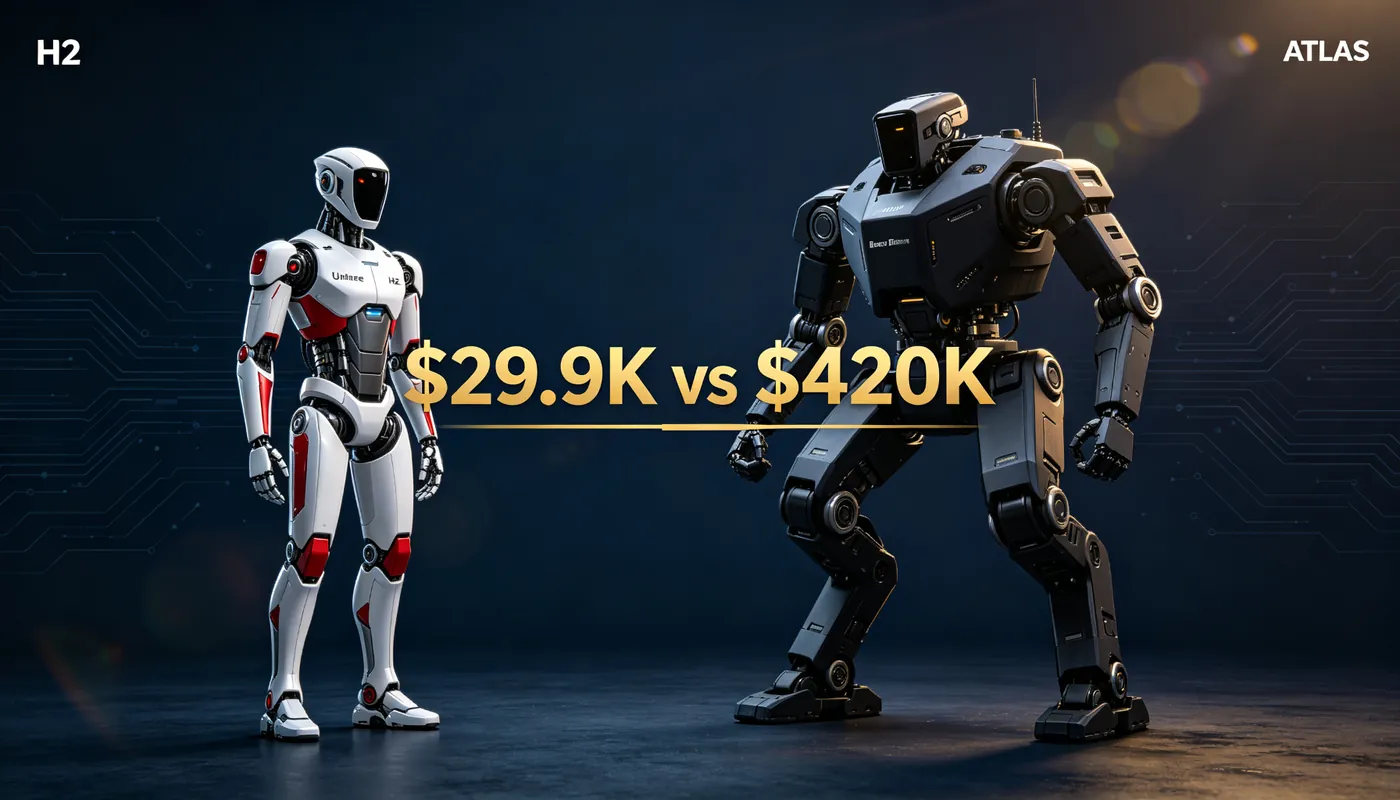
Unitree sells a full-size humanoid for $29,900. Boston Dynamics will not sell you an Atlas — and industry estimates put it near $420,000. The 14x gap, dimension by dimension.
Japan's Harmonic Drive holds 58% of global reducer revenue. China's Leaderdrive is No.2 globally, No.1 at home — and owns 80-90% of Chinese humanoids. The robot-joint war, dimension by dimension.
UR invented the cobot category and still defines its software — but Chinese brands now match specs at 40-70% lower prices and hold ~85% of China's market. Specs, price and ecosystem, side by side.
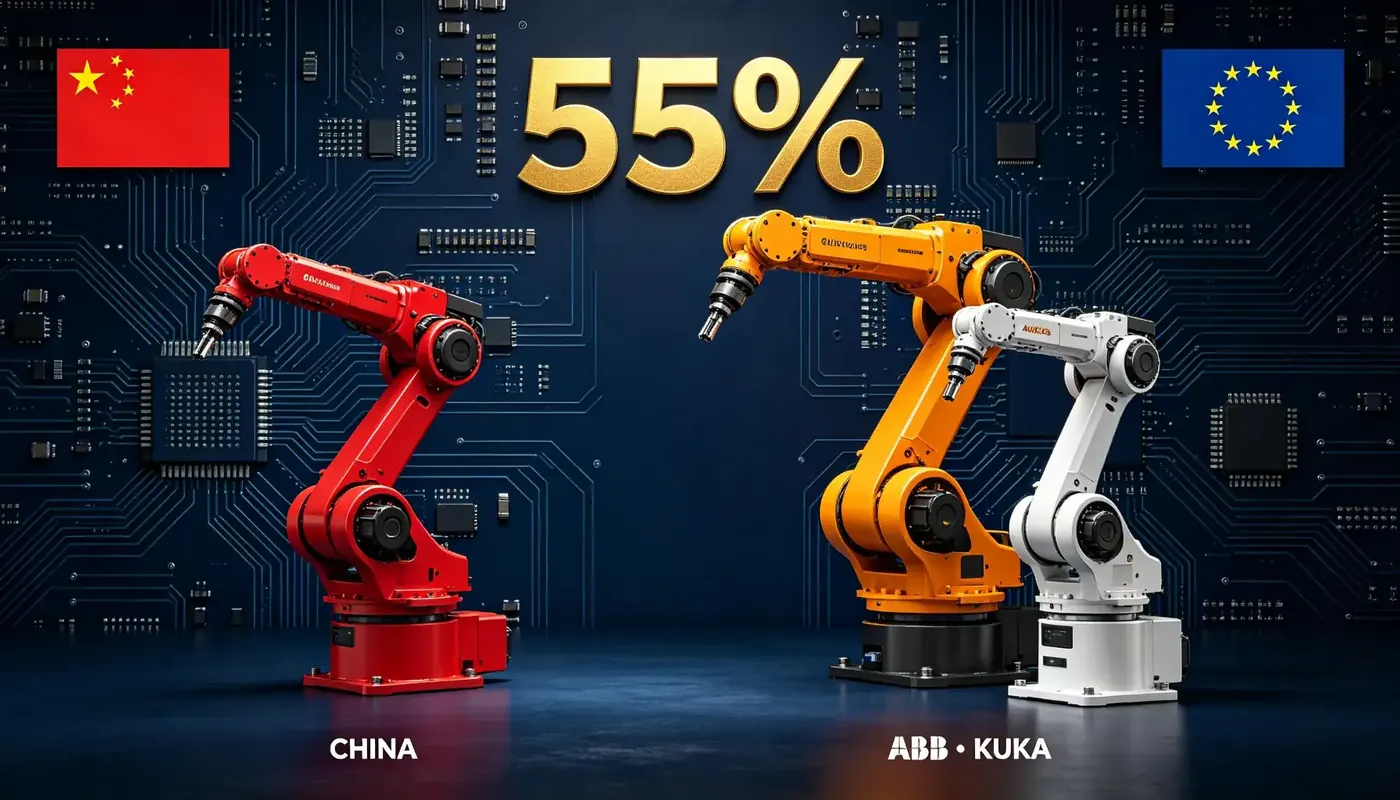
For the first time, Chinese brands out-ship foreign brands at home — 55% in Q1 2026. How Estun, Inovance and JAKA beat ABB, KUKA and Fanuc, where Europe still rules, and what a buyer should do.
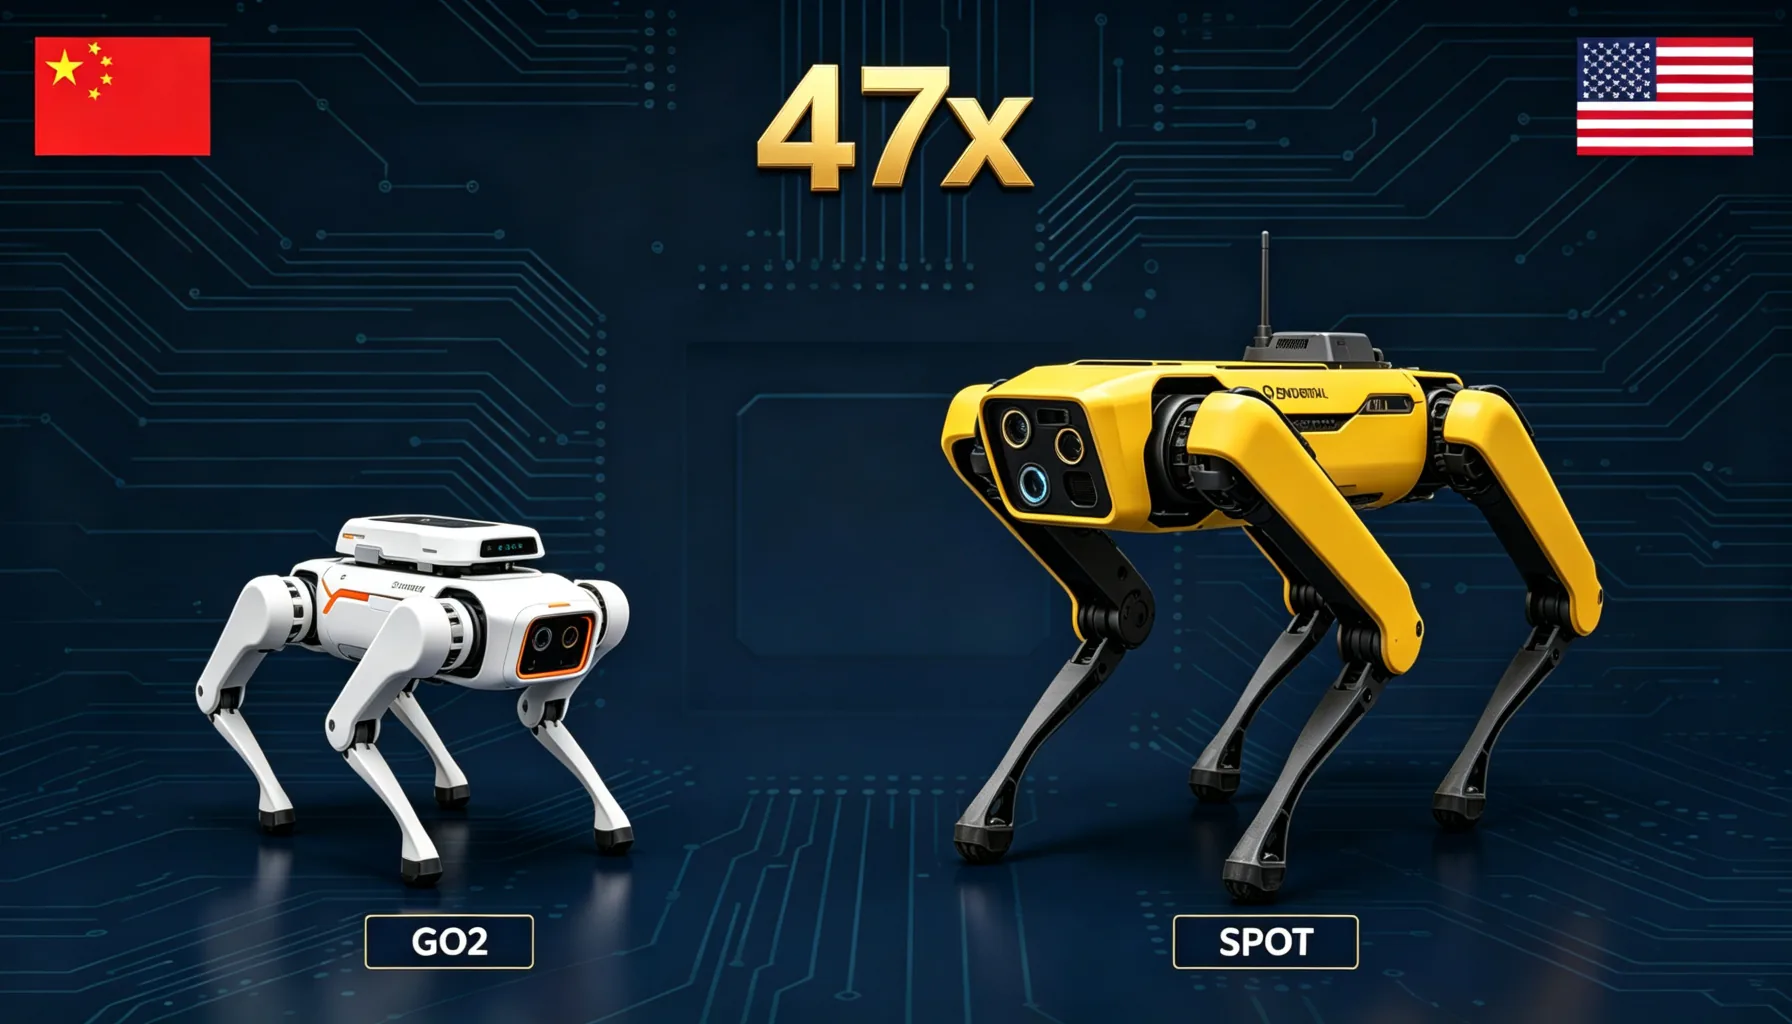
Go2 starts at $1,600 and ships by the tens of thousands. Spot starts at $74,500 and runs oil rigs. A 47x price gap — specs, software, deployment proof and who should buy which.
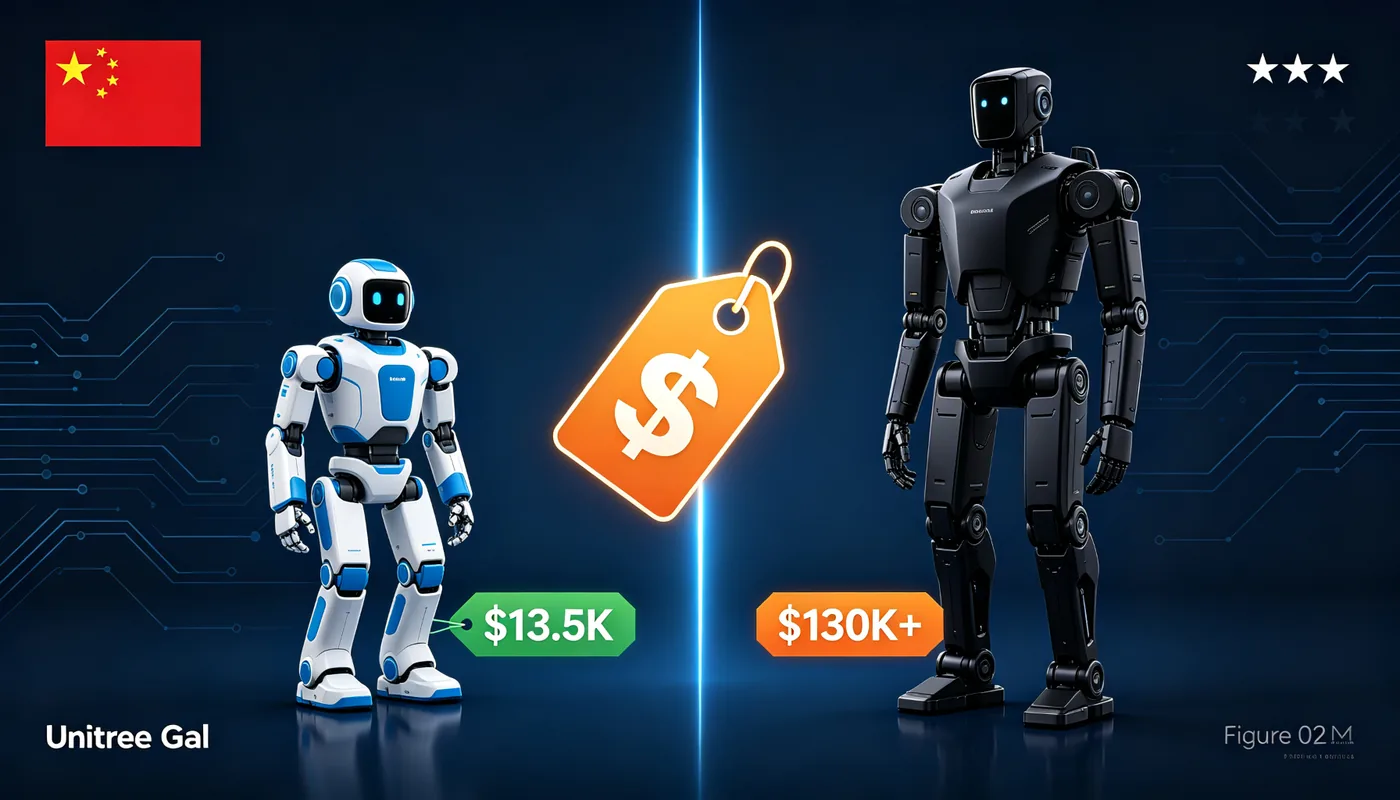
The world's most-shipped humanoid ($13.5K, open SDK, anyone can buy) against America's flagship enterprise humanoid (est. $130K+, Helix AI, BMW-only). Spec-by-spec: price, payload, hands, AI and the two production philosophies.
Only three US-listed China plays carry real robot stories: XPeng's IRON and $900M round, Faraday Future's nine-robot launch on Sep 19, and Hesai's robot-LiDAR dominance — plus the Unitree IPO cautionary tale.
While Tesla and Unitree cram AI into robot bodies, CloudMinds and the ¥3B-seed-round Datta Robotics bet the brain belongs in the cloud — a ¥412.6B domestic market and a 23.1% CAGR behind them.
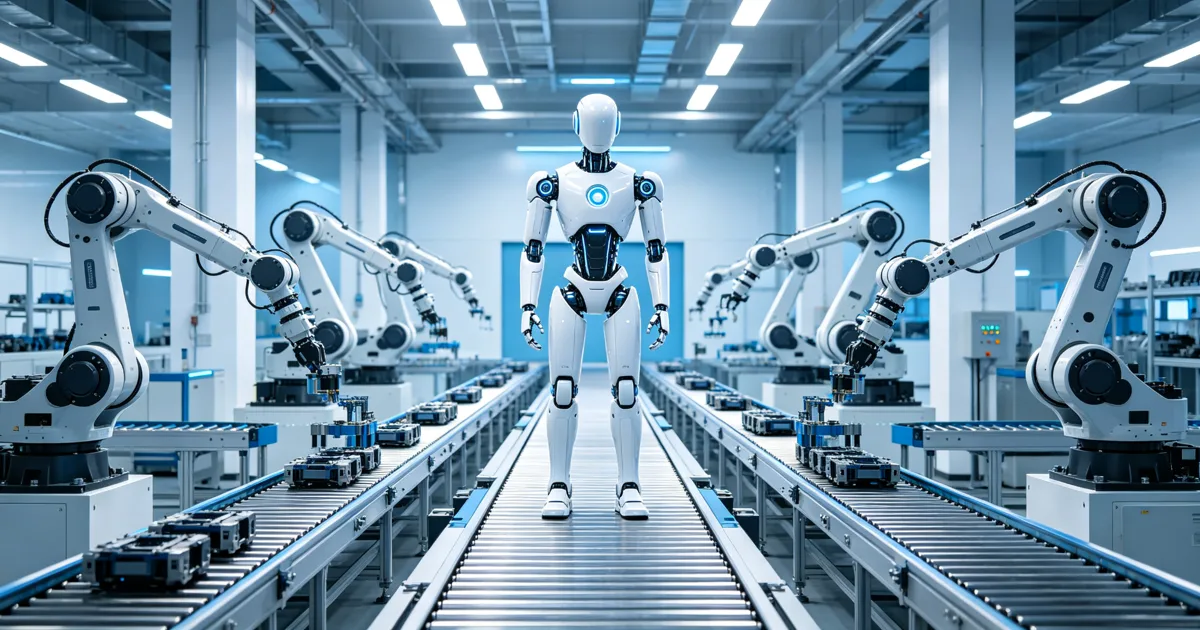
World's first automated humanoid production line went live Sep 8, 2026 — >80% core automation, an 85% overlap with XPENG's EV supply chain, and a robot that walked off the line on its own.
Hugging Face's Microduck sold $2.6M in 24 hours. Seeed Studio builds it, Rockchip RK3566 powers it, Radxa boards it.
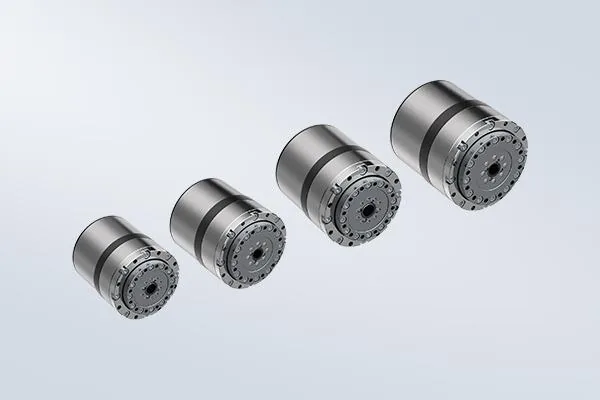
Actuators take 40-56% of a humanoid's BOM. Tuopu, Sanhua, Leaderdrive and Zhongda Leader now own the muscle.
Where the $20,000 goes — a component-by-component teardown of actuators, hands, sensors and compute, with China vs Western prices.
Orbbec (>70% service-robot share, inside AgiBot/Unitree/UBTech) and Mech-Mind (29,000+ deployments) now make the eyes of Chinese robots.
Estun leads all-brand China shipments; Fanuc falls to 9%, ABB sells robotics to SoftBank.
Toumai (200+ orders) and TiRobot (~40% ortho share) take on Intuitive at 40-60% less.
0.5-2 kWh packs, high-nickel NMC vs LFP vs solid-state, and why CATL quietly supplies it all.
Frameless torque + coreless motors, ~12% of BOM. Moons' and Kinco take on the Swiss and American benchmarks.
~72 precision bearings per humanoid. HONB, LYC and ZWZ now supply the domestic chain at scale.
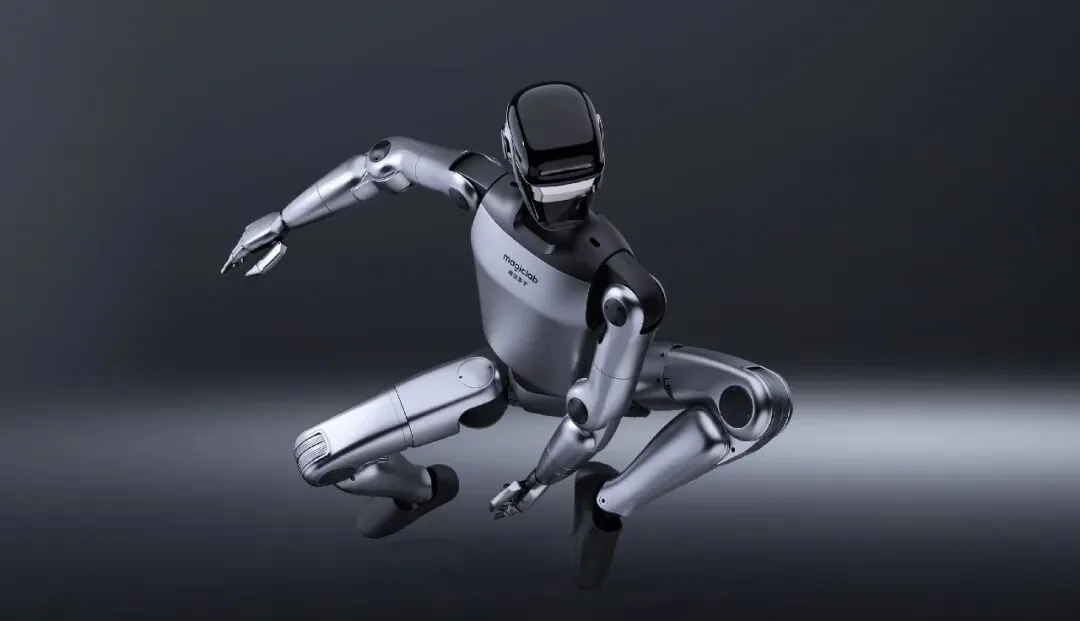
The world's best-selling vacuum maker spun out Magic Atom — ¥500M Series A, X1 and Z1 humanoids already on factory lines.
The pillar guide — reducers, actuators, encoders, screws, hands, sensors and LiDAR. Who leads every component in 2026.
Every joint needs eyes. Inovance, HCFA and Yuheng are closing Heidenhain's gap — 54 encoders per humanoid.
Zhongda Leader owns Unitree's heavy joints — a 3.2B RMB contract behind 110,000 robots.
Touch sensors were China's #4 bottleneck tech in 2018 — 90% imported. Now 100% domestic. Blue Dot, Kunwei, PaXini and Hanwei lead.
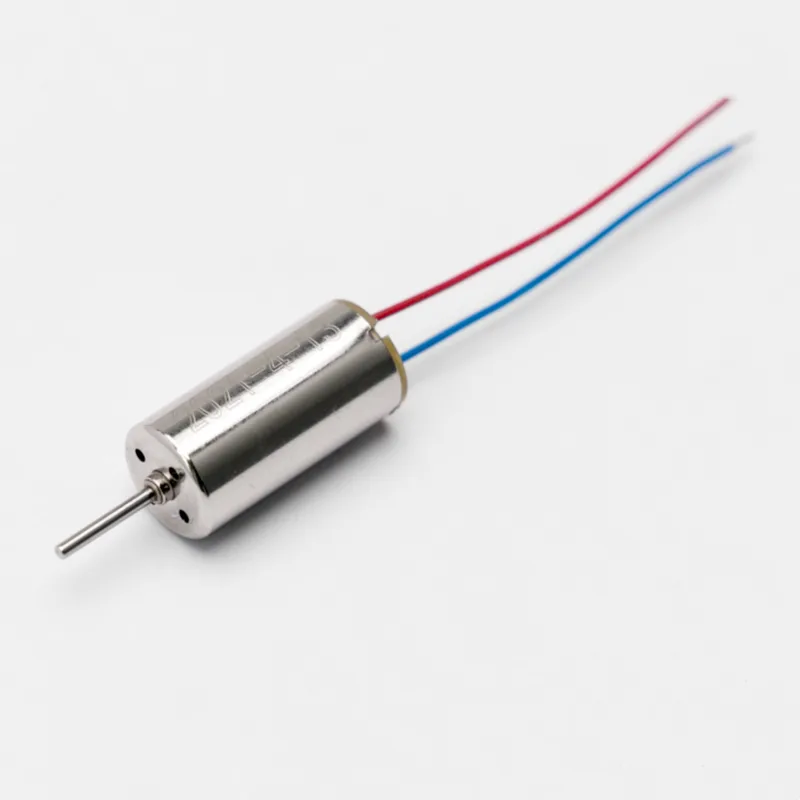
Every finger of a robot hand runs on a coreless motor. MOONS', Zhaowei and Leadshine are breaking Maxon's grip — and cutting prices 67%.
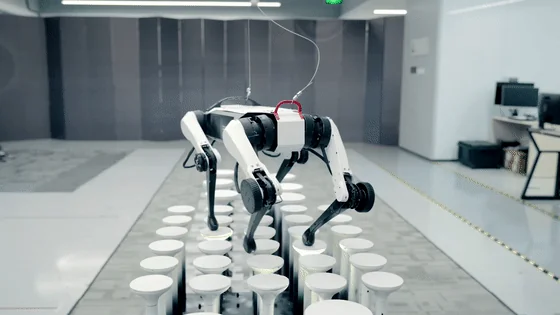
China's biggest tech giant refuses to mass-produce robots. Inside Xiao Liu, Tairos and its embodied-AI "brain" strategy.
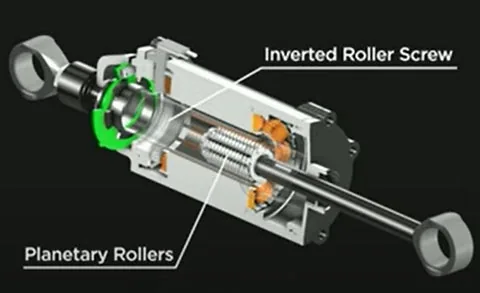
~14 lead screws, ~19% of a humanoid's cost. China's Nanjing Tech, Best Precision, Wuzhou Xinchun and Tuopu are breaking Europe's grip.
The muscles behind Tesla Optimus and China's humanoid wave — Sanhua, Tuopu, Inovance, Kinco, ranked.
Harmonics get the headlines; RV reducers carry the weight. The heavy-duty joint suppliers, ranked.
The vacuum giant made $4B in 2025, ~80% overseas — and now builds humanoids via Magic Atom. Full story of Yu Hao's empire.
The vacuum giant made $4B in 2025, ~80% overseas — and now builds humanoids via Magic Atom. Full story of Yu Hao's empire.
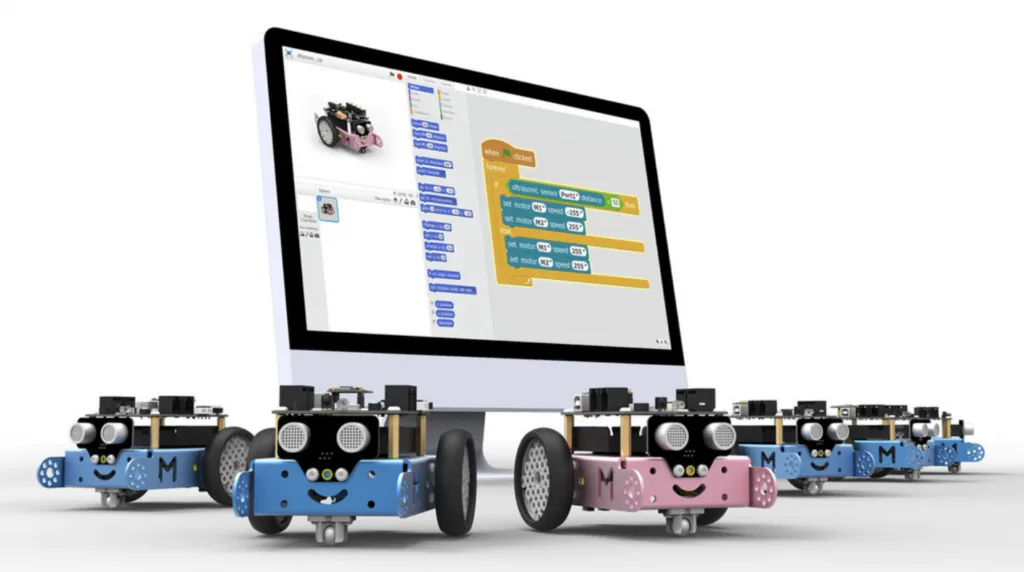
$244M today, $1.16B by 2035 — UBTECH, Makeblock, DJI Education and the kit makers training China's next engineers.
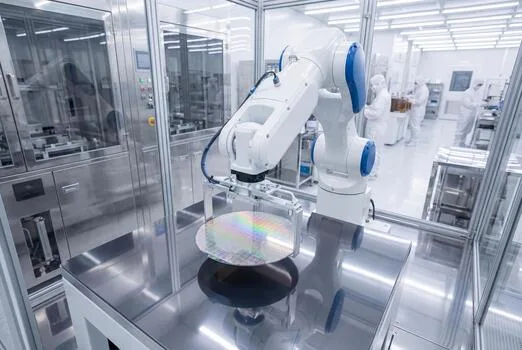
US$1.7B and growing 20.8% a year — Topstar, SIASUN and Estun now move wafers inside China's newest fabs.
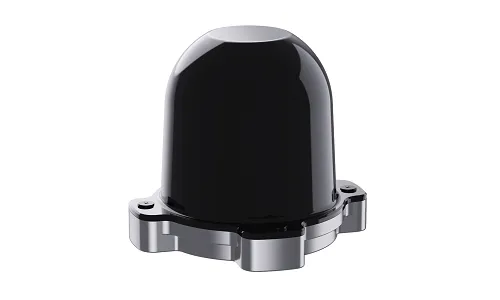
Hesai, RoboSense, Seyond and Huawei control the world's LiDAR — and now the eyes of robots. The 2026 supplier guide.
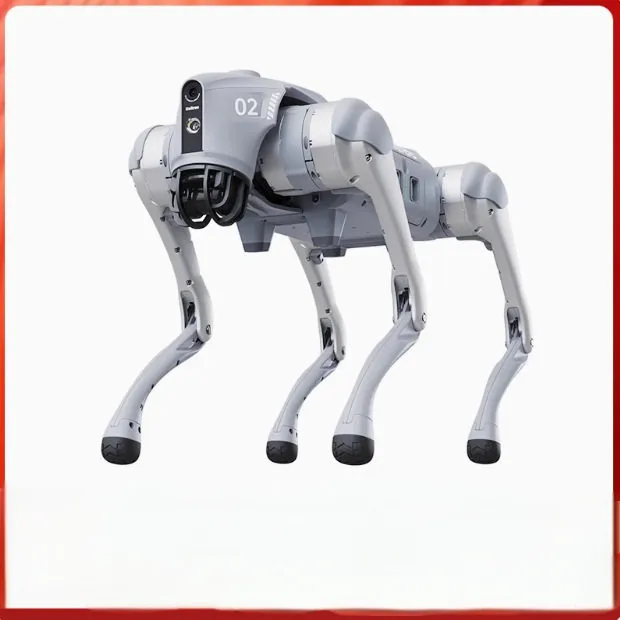
China's two most popular robot dogs, head to head — specs, price, sensors, AI and which one to buy in 2026.
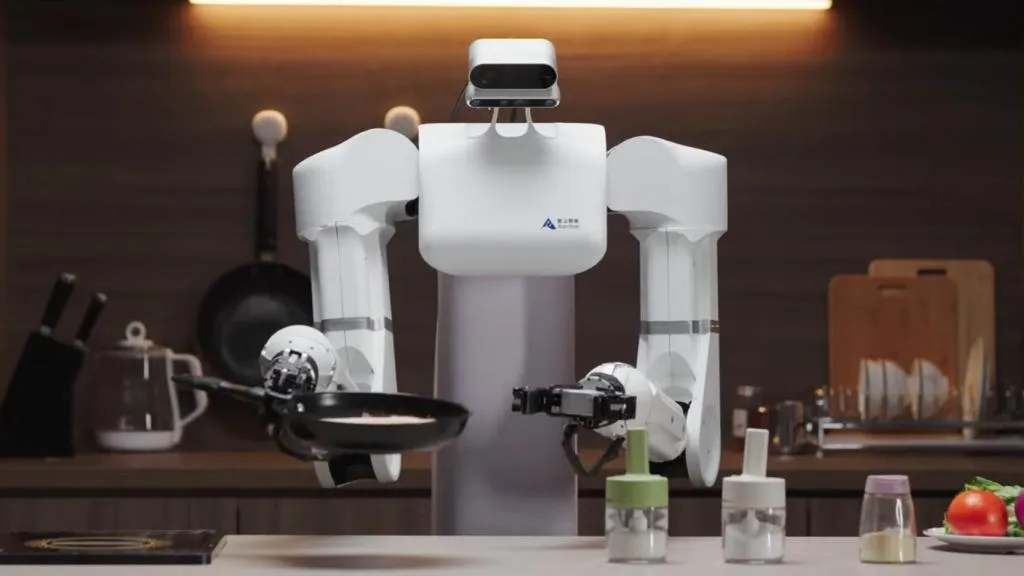
Inspire Robots, Linkerbot, PaXini and the supply chain now shipping humanoid hands by the tens of thousands.
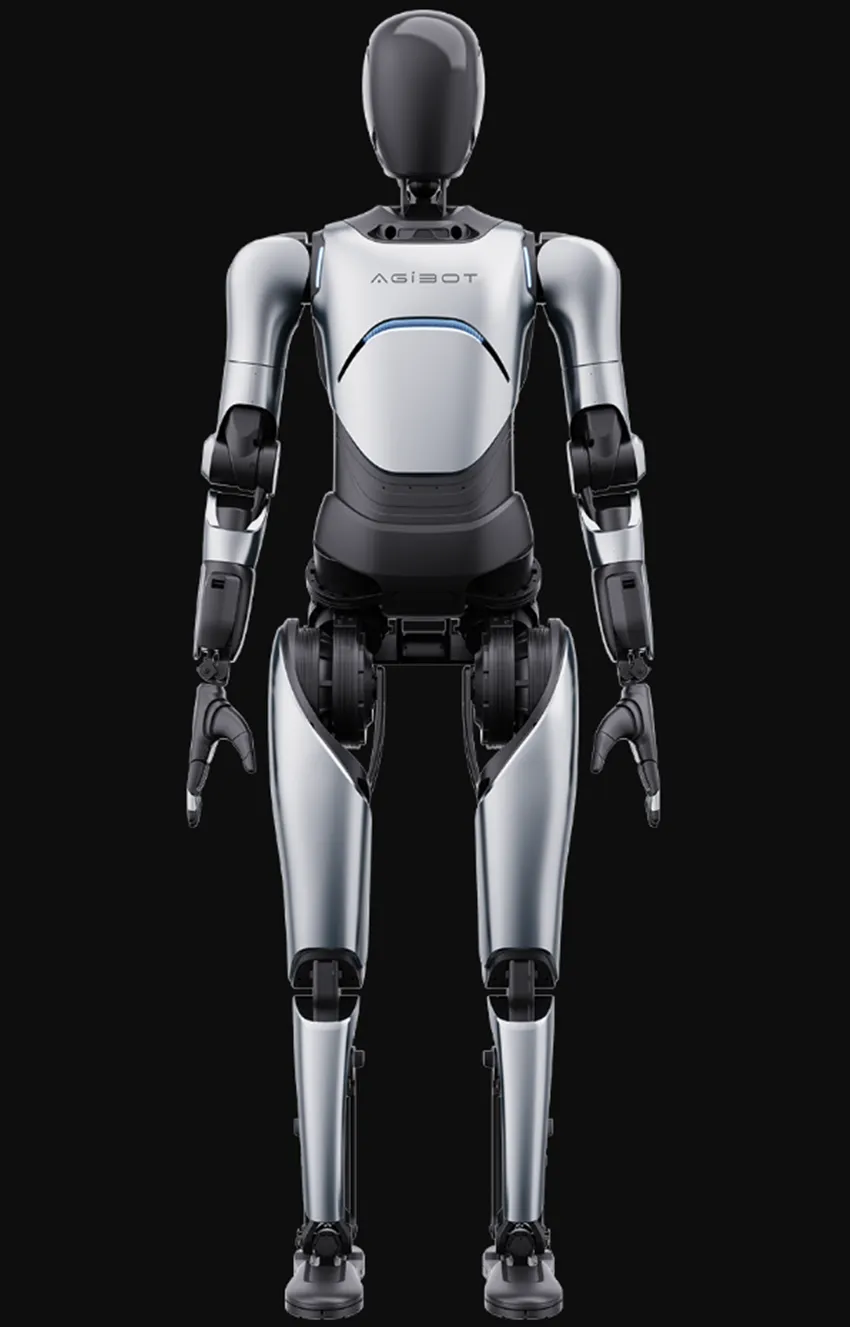
China's two best-known humanoids, compared — full-size commercial flagship vs the $16k volume king. Specs, price and which fits your use case.
Every Go2 spec that matters — size, 12 DOF, 45 N·m joints, 4D LiDAR L2, speed, payload, price and all model variants.
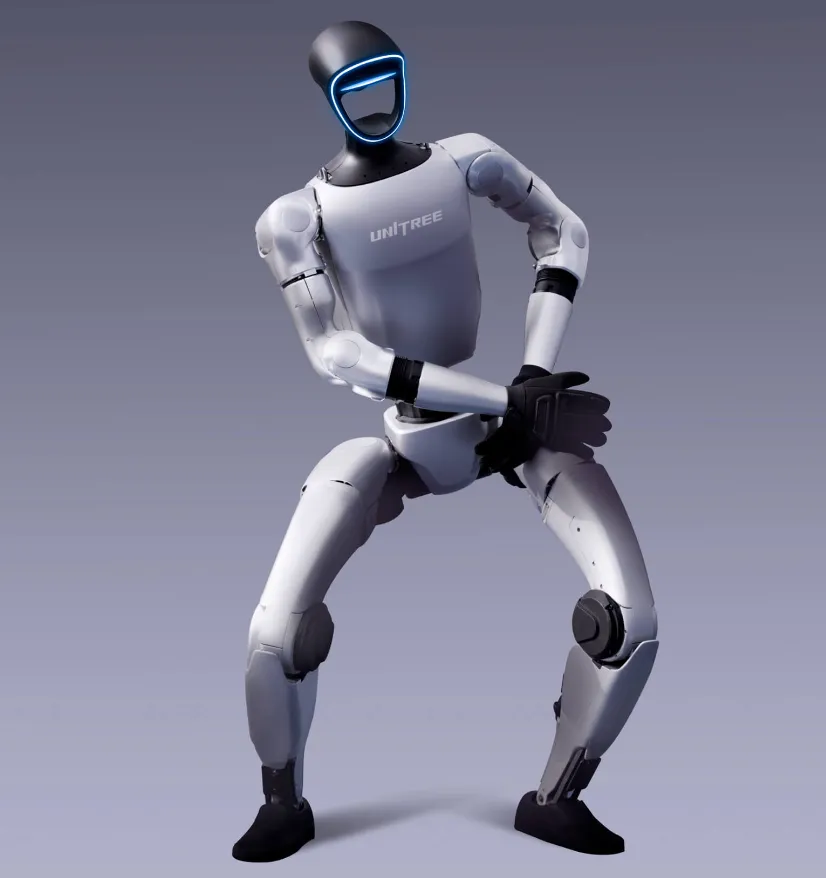
Every G1 spec — height, weight, degrees of freedom, hands, battery, price — and how it beats Tesla Optimus on cost.
Two Chinese humanoids, two strategies. The honest comparison of the volume king and the industrial challenger.
The 2026 supplier list — Leaderdrive, Laifual, Haozhi and more — that now powers China's robot joints.
Who makes the screws inside Chinese humanoids? Hengli, XCC, Best Precision and the picks-and-shovels play.
How national, city and provincial money plus industrial parks are backing the humanoid bet.
China shipped most of the world's humanoid robots in 2025. Meet the seven companies leading the race — and the one force that will decide who wins.
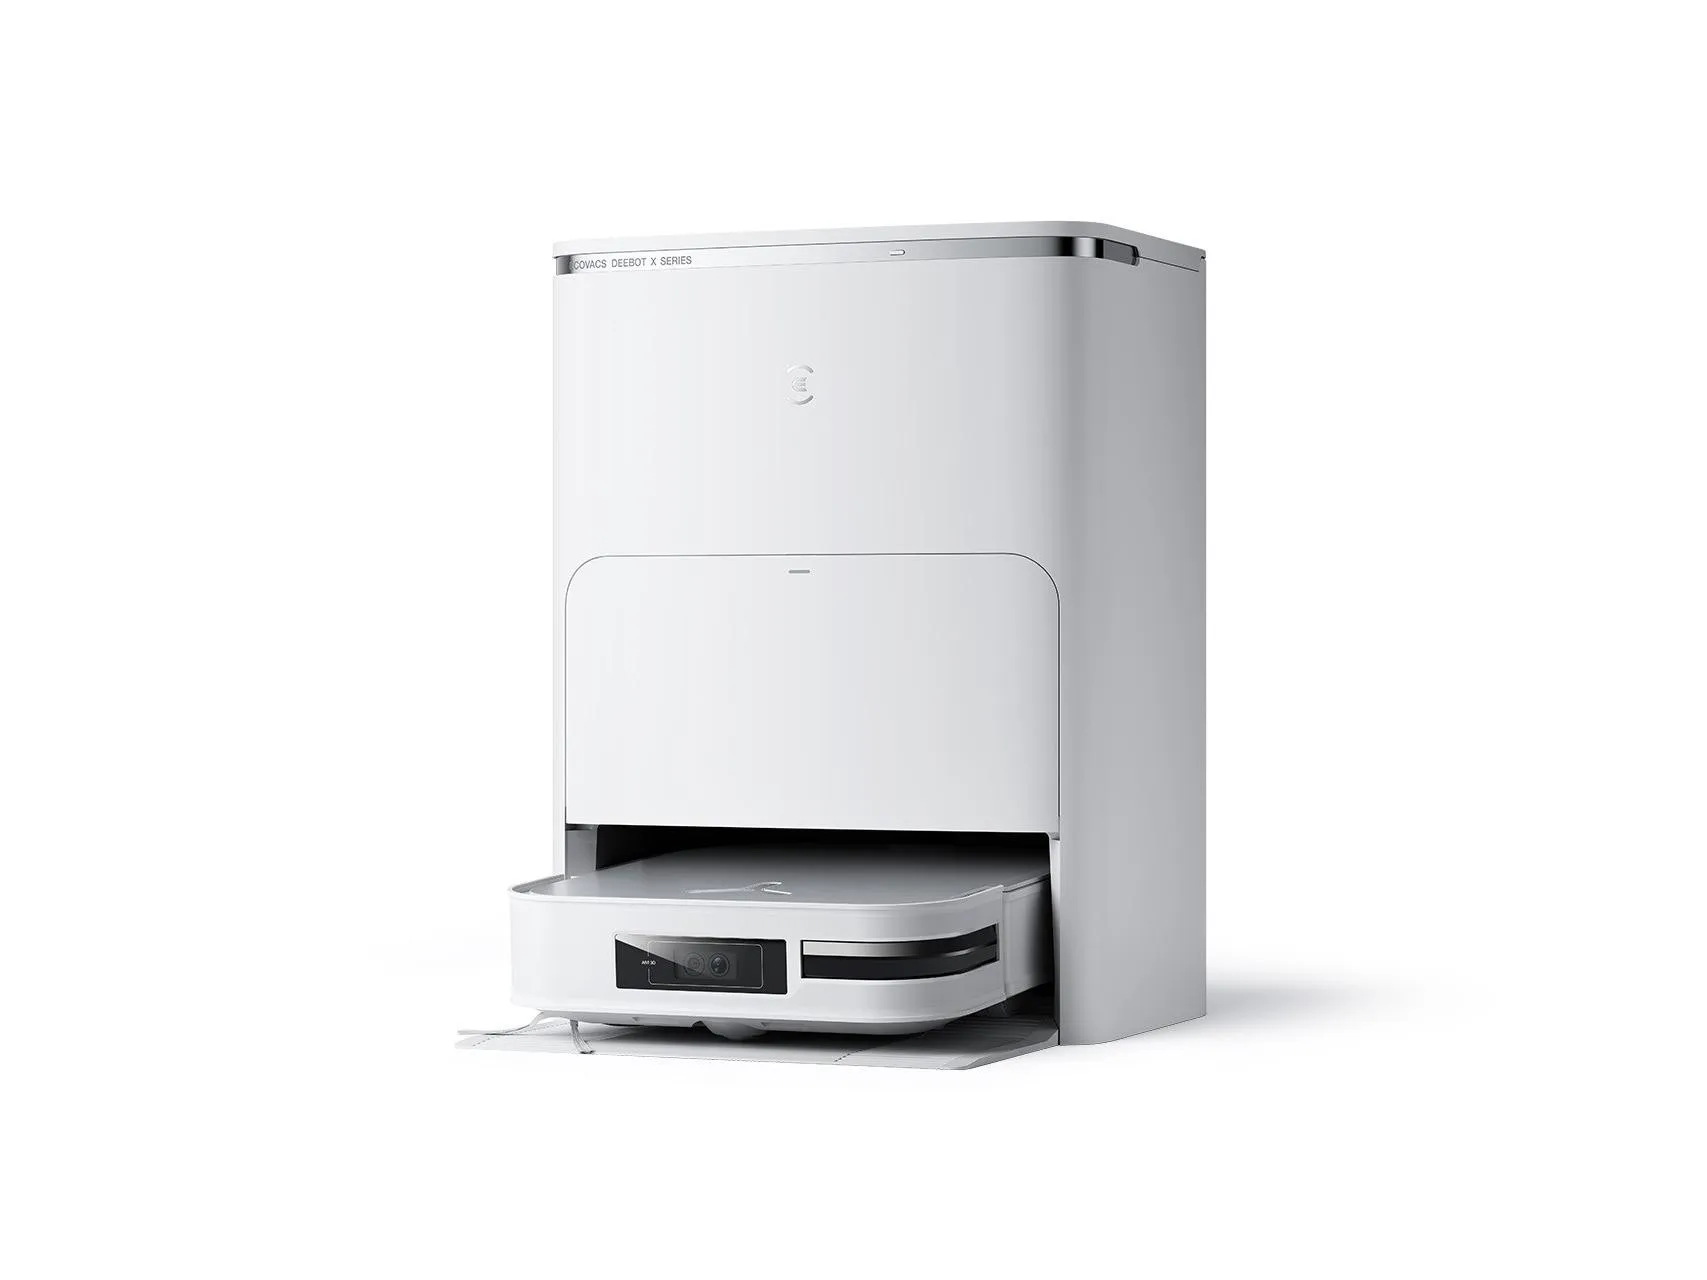
Before the humanoid hype, there was a quieter Chinese victory. How Ecovacs, Roborock and Narwal turned a niche gadget into a global category.
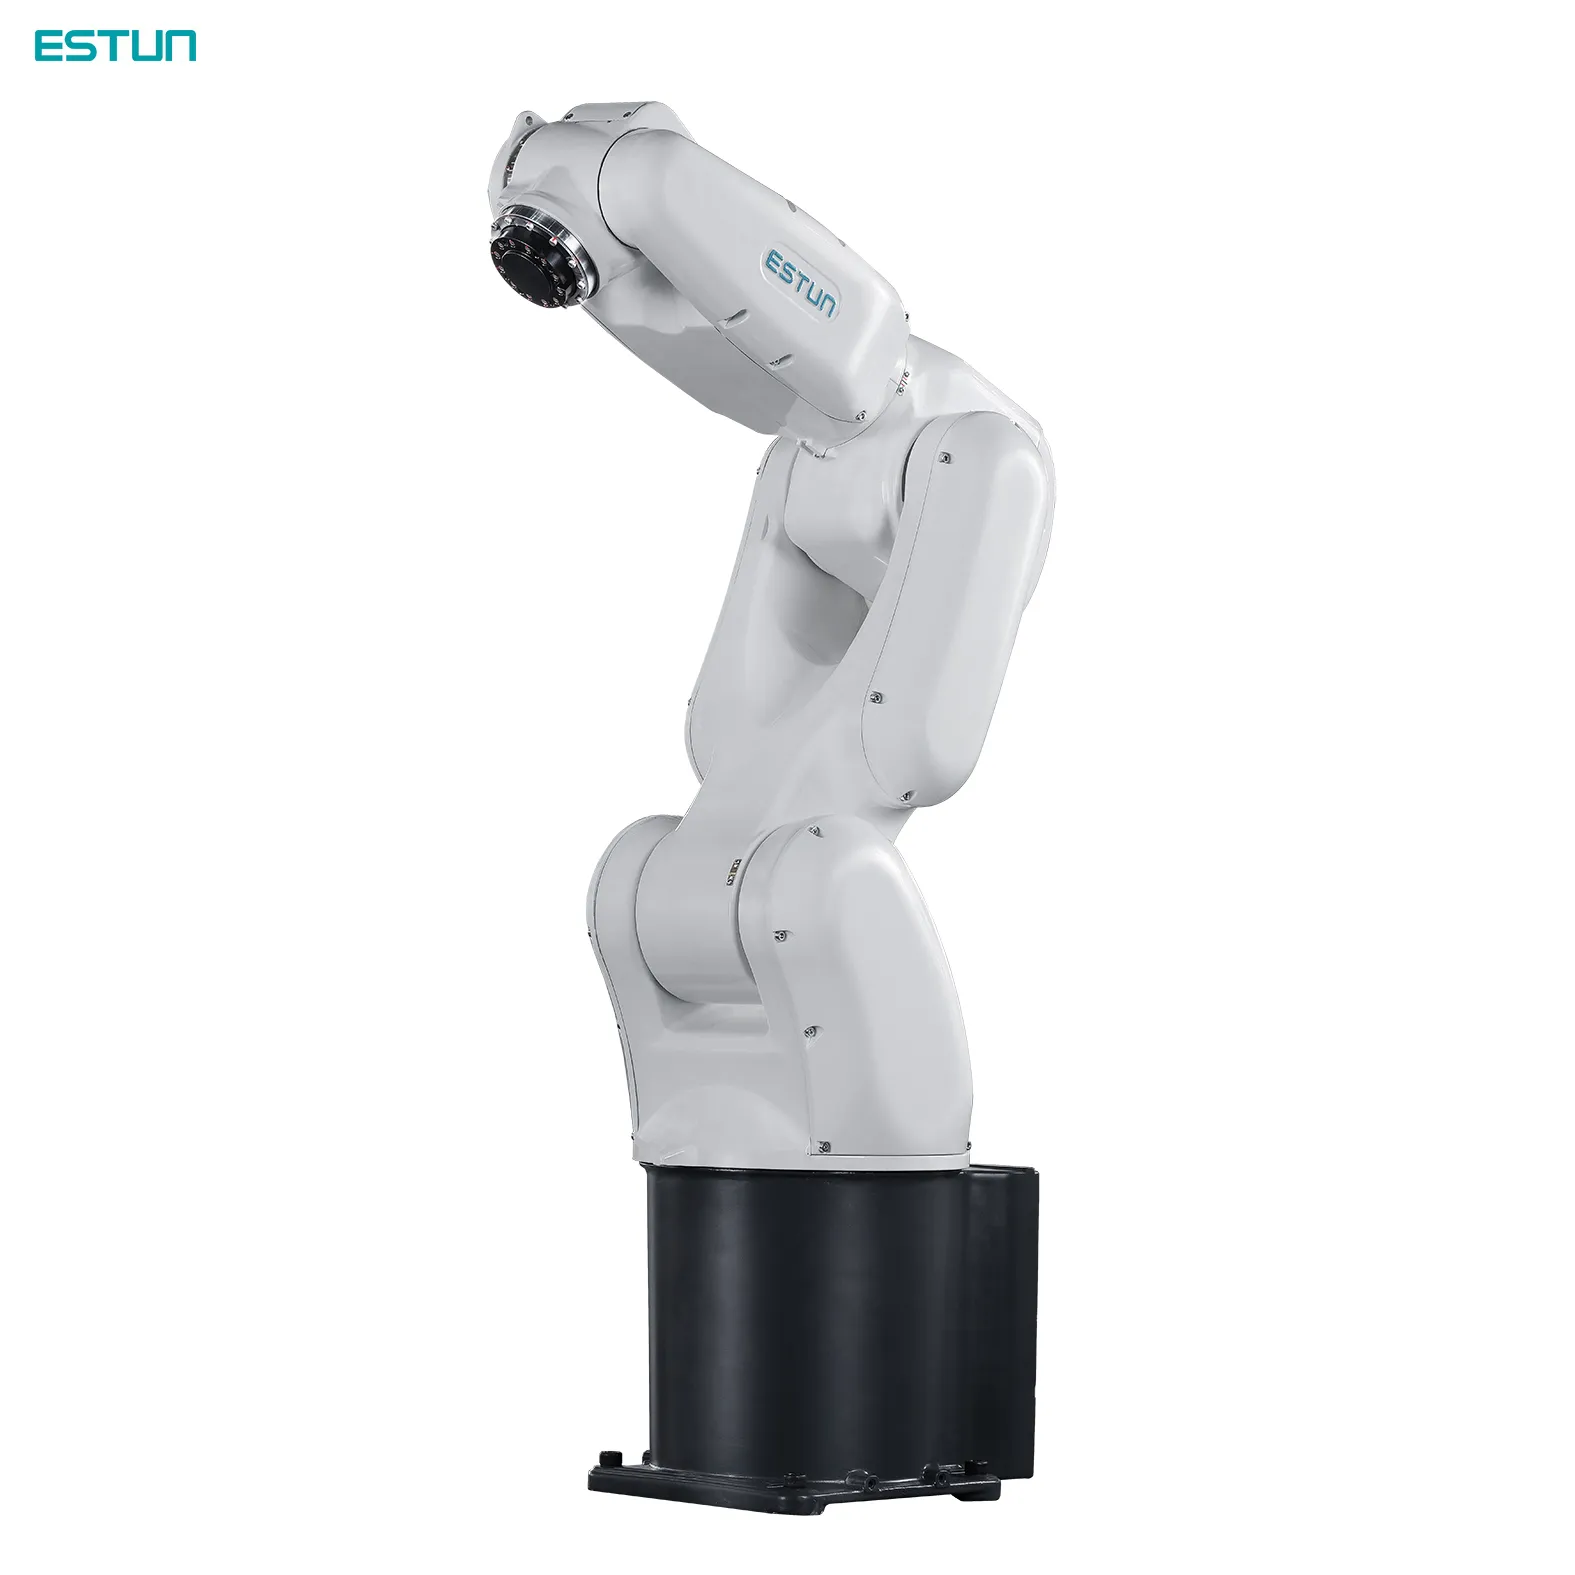
In 2025, Chinese brands beat ABB, FANUC, Yaskawa and KUKA on their home turf for the first time. How Estun, Inovance and SIASUN did it.
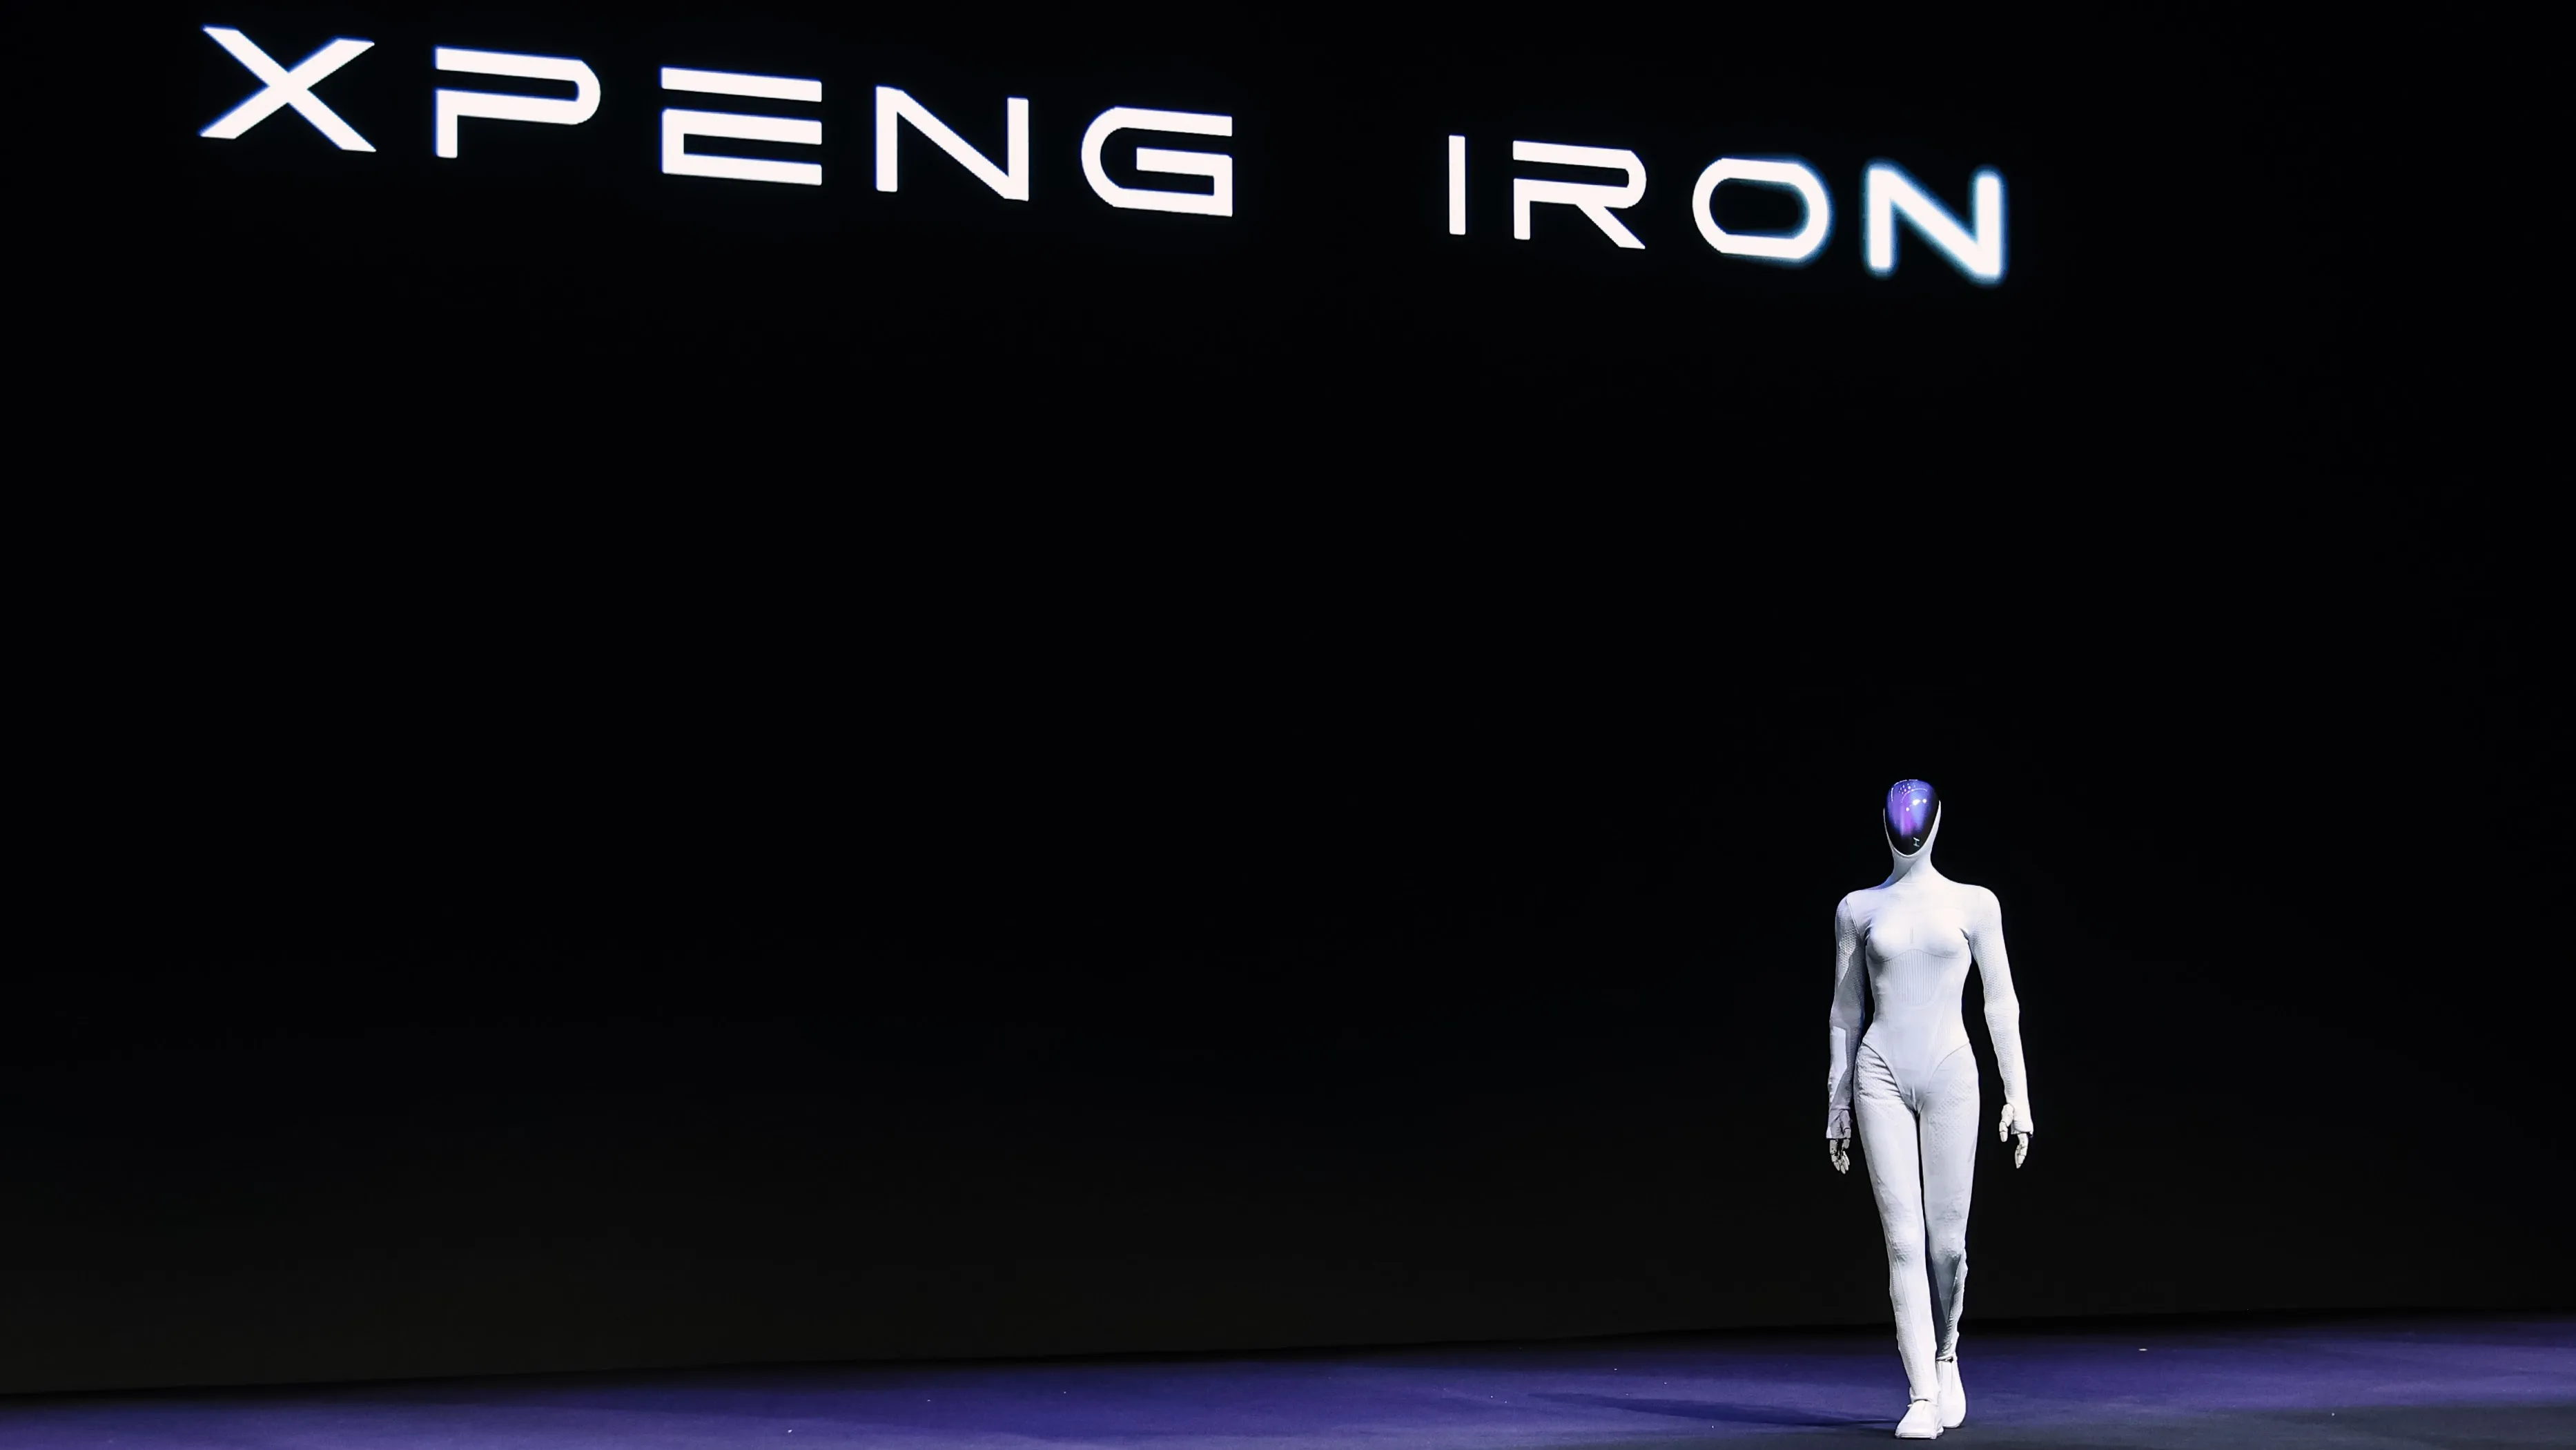
More than ¥100 billion poured into China's humanoid startups in two years. The funding mechanics behind the boom — and where the money is heading.
RMB 300B+ 2025 revenue, 28% of global demand, and the fastest-moving niches — cloud, educational and clean-room robots — sized with sources.
22,000-36,000 humanoids shipped in H1 2026 — 86-97% of them Chinese. Figure is valued at $39B and Tesla targets 50,000 Optimus units, but China is shipping volume.
IDC: RMB 1.07B hardware sales in H1 2025, RMB 3.9B by 2029. Policy drivers, UBTECH/Makeblock/Dobot, and China vs. the US and Japan.
Read the fundamentals before the deep dives — the history, the people and the full landscape.
Geek+, Quicktron, Seer Robotics and VisionNav vs Western AMR leaders - specs, price, navigation and where Chinese vendors already win.
2026-09-23
From the first Chinese robot in 1980 to the humanoid mass-production era — four decades in six acts.
The "Father of Chinese Robotics," the professor who spawned DJI, and the 20-something PhDs raising fortunes.
The complete landscape — humanoid, industrial, service, aerial and component players.
From 10 m/s humanoids to banana-peeling robotic hands — the hardware defining the frontier.
This site is built for investors, engineers, students and the curious. Bookmark it — new insights drop as the industry moves.